

👋 Howdy Partner,
A few weeks ago, Brookfield walked away from The Beaudry, a 64-story, $600 million luxury apartment tower in downtown Los Angeles.
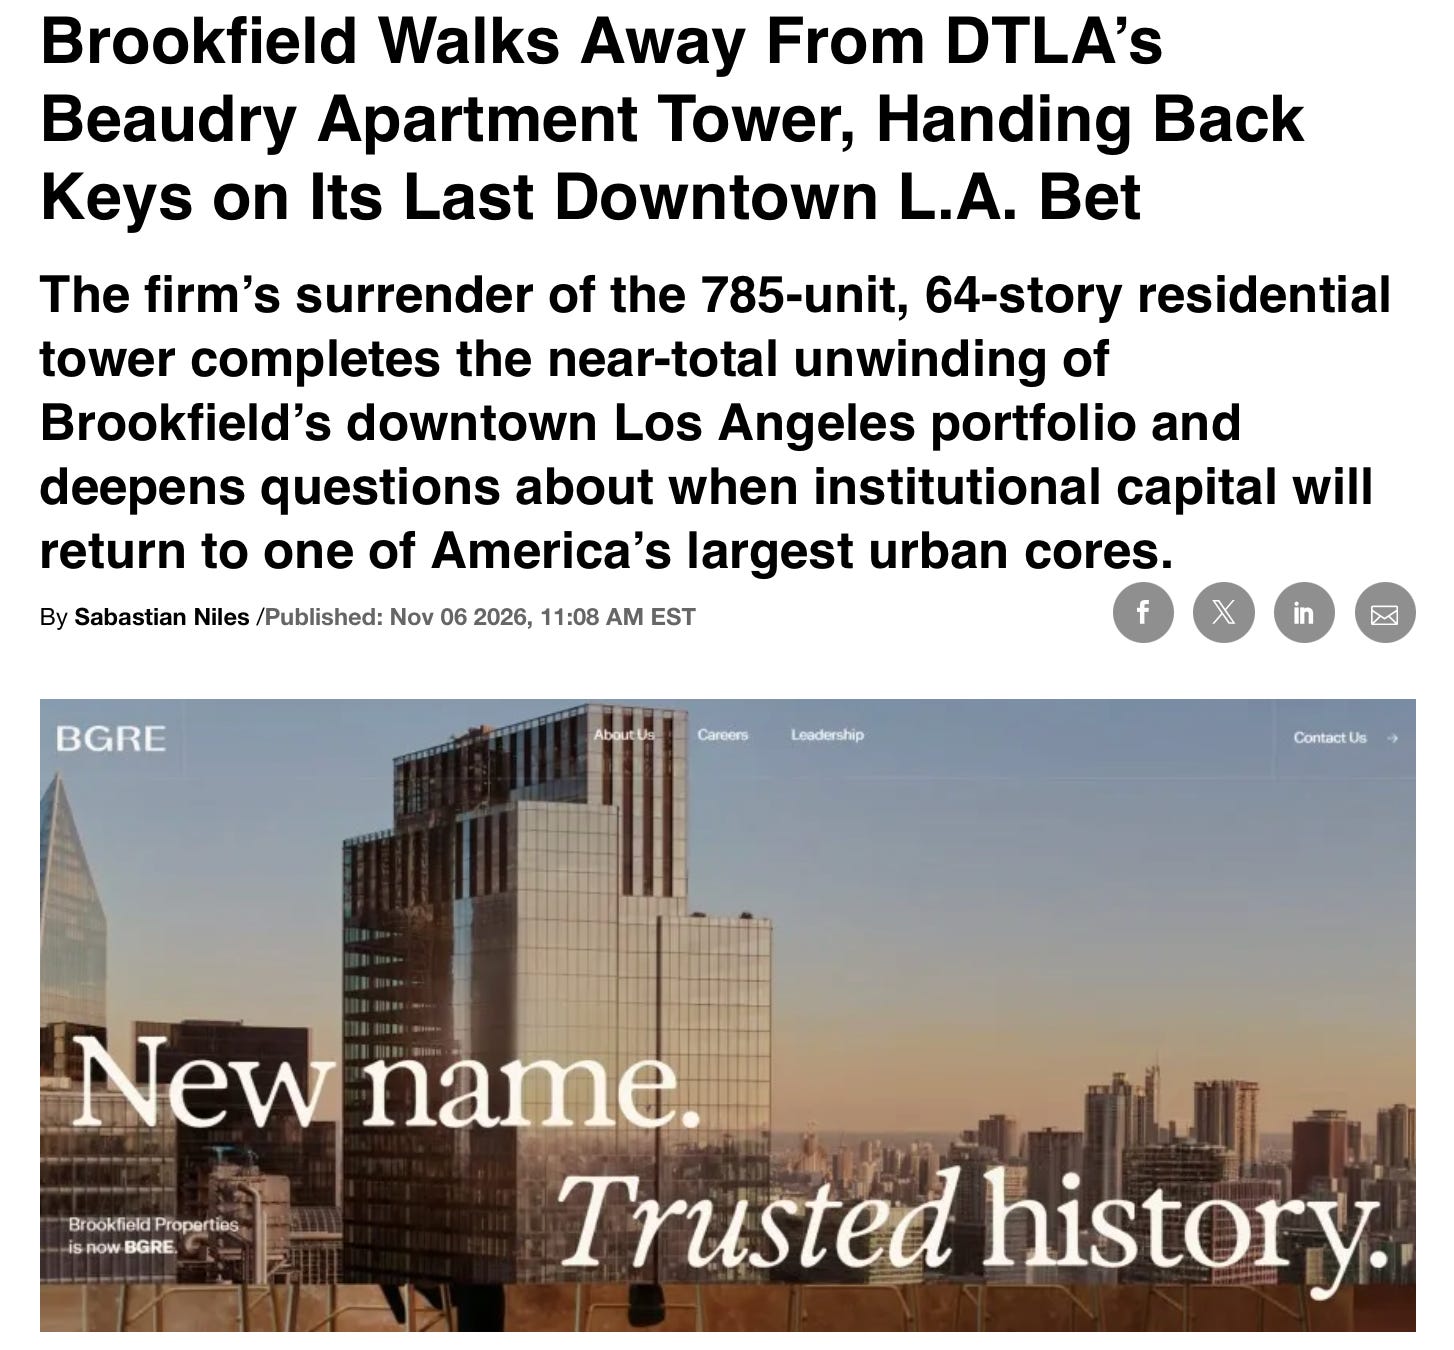
Here’s the crazy part: the building is 95% leased.
In residential real estate, a 95% occupancy rate is a home run.
So why would one of the smartest real estate operators in the world just hand the keys back to the bank?
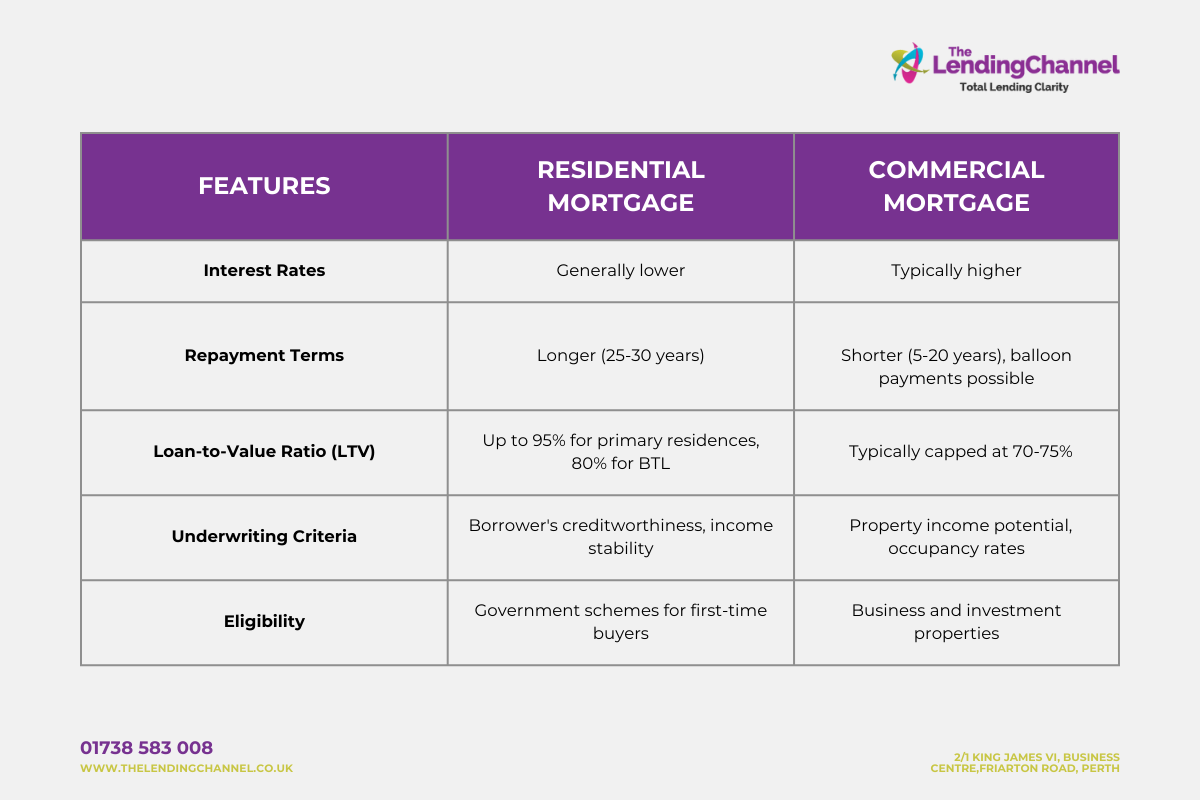
Because commercial real estate debt doesn’t work like your home mortgage.
Most homeowners lock in a 30-year fixed-rate loan. Once you sign the papers, you don’t care if interest rates double next year. Your payment never changes.
Commercial real estate loans are usually short-term, anywhere from 3 to 7 years.
When that term ends, the owner has to refinance the remaining balance at whatever today’s interest rates happen to be.
During the zero-interest-rate era, investors bought up properties at sky-high prices because debt was virtually free.
Now, those loans are coming due.
A property that printed money at a 3% interest rate becomes a money loser when it has to be refinanced at 7% or 8%.
Even if the building is packed with tenants, the math doesn’t work.
For a while, banks tried to kick the can down the road.
Now, they’re willing to book losses just to get these bad loans off their books.
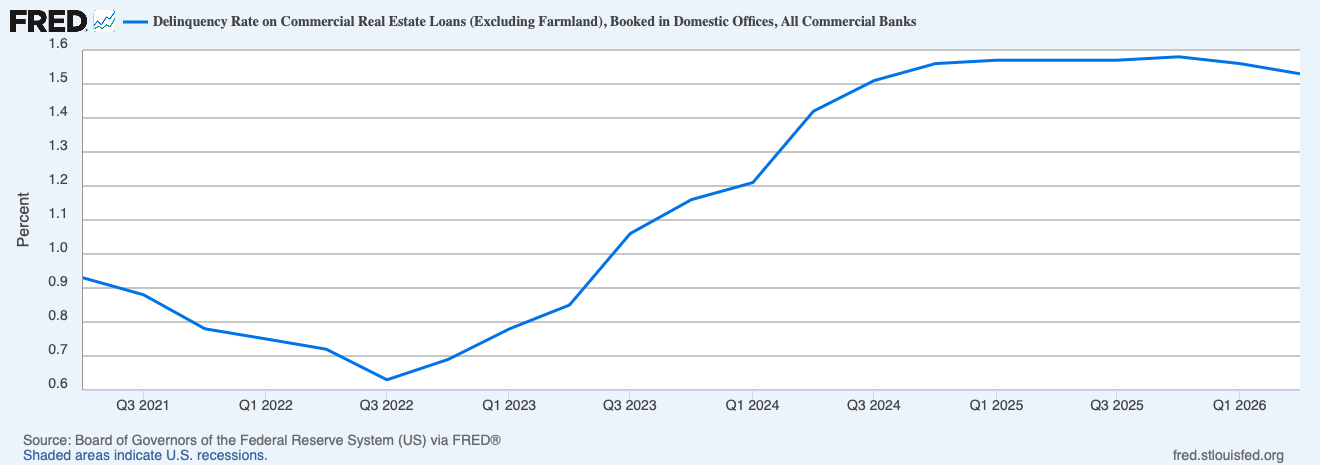
Forced selling has officially begun.
Most investors see headlines like this and run for the hills. They dump anything remotely connected to real estate.
Dividend investors should do the exact opposite, if you know what to look for.
Tough times like this separate landlords into two groups:
Over-leveraged operators facing near-term debt maturities who are forced to sell their best properties at fire-sale prices just to survive.
Disciplined REITs with fortress balance sheets, fixed-rate debt, and plenty of cash on hand.
The first group will try to survive.
The second group will go on offense.
They’ll scoop up prime real estate at distressed prices, locking in higher yields for the next decade.
So, what should you look for in a REIT right now?
A fortress balance sheet with mostly fixed-rate debt and no major maturities coming due soon.
Essential tenants that sell everyday goods people still buy in a recession.
Disciplined management that raised capital before valuations dropped, giving them dry powder to buy while everyone else is selling.
Insider buying with management putting their own money on the line when Mr. Market puts the stock on sale.
We Just Found One, And We’re Buying It Today.
A year ago, I did a full deep dive on one of the highest-quality net-lease REITs on the market.
It owns over 2,800 free-standing properties leased to rock-solid, e-commerce-resistant retailers.
Back then, I loved the business, but the price wasn’t quite right. So we waited.
Over the past year, the stock price drifted down while the company kept raising its dividend.
Today, we’re adding it to the Compounding Dividends High Yield Portfolio.
If you want to see the ticker, the full updated valuation math, and get immediate access to our entire High Yield Portfolio, become a Partner today.
One Dividend At A Time,
-TJ
Used sources
Interactive Brokers: Portfolio data and executing all transactions
Fiscal.ai: Financial data
Disclaimer
As a reader of Compounding Dividends, you agree with our disclaimer. You can read the full disclaimer here.