

👋 Howdy Partner,
Screens are a great tool to find investing ideas.
When you screen for income, it’s easy to get pulled towards the highest yields you can find.
But there’s a much better way, and today I’ll show it to you.
The Second Quintile
Historically, the secret to outperforming the market isn’t buying the top 20% of high dividend yielders.
It’s buying the next 20%, the Second Quintile.
Hartford Funds looked at the performance from 1930 to 2023.
$1,000 in the S&P 500 grew to $8.6 million
$1,000 in the Second Quintile grew to $31.2 million
That is nearly 4x more wealth.

Why it Works
The Second Quintile is a great place to invest for several reasons:
Safety: You avoid the yield traps and distressed companies in the top tier.
Quality: You own profitable companies with enough cash flow to pay you and grow the business.
Stability: Historically, this group has the fewest negative years of any quintile.
That third one is huge - protect the downside and the upside takes care of itself.
These companies tend to have a much lower Payout Ratio than the first quintile as well.
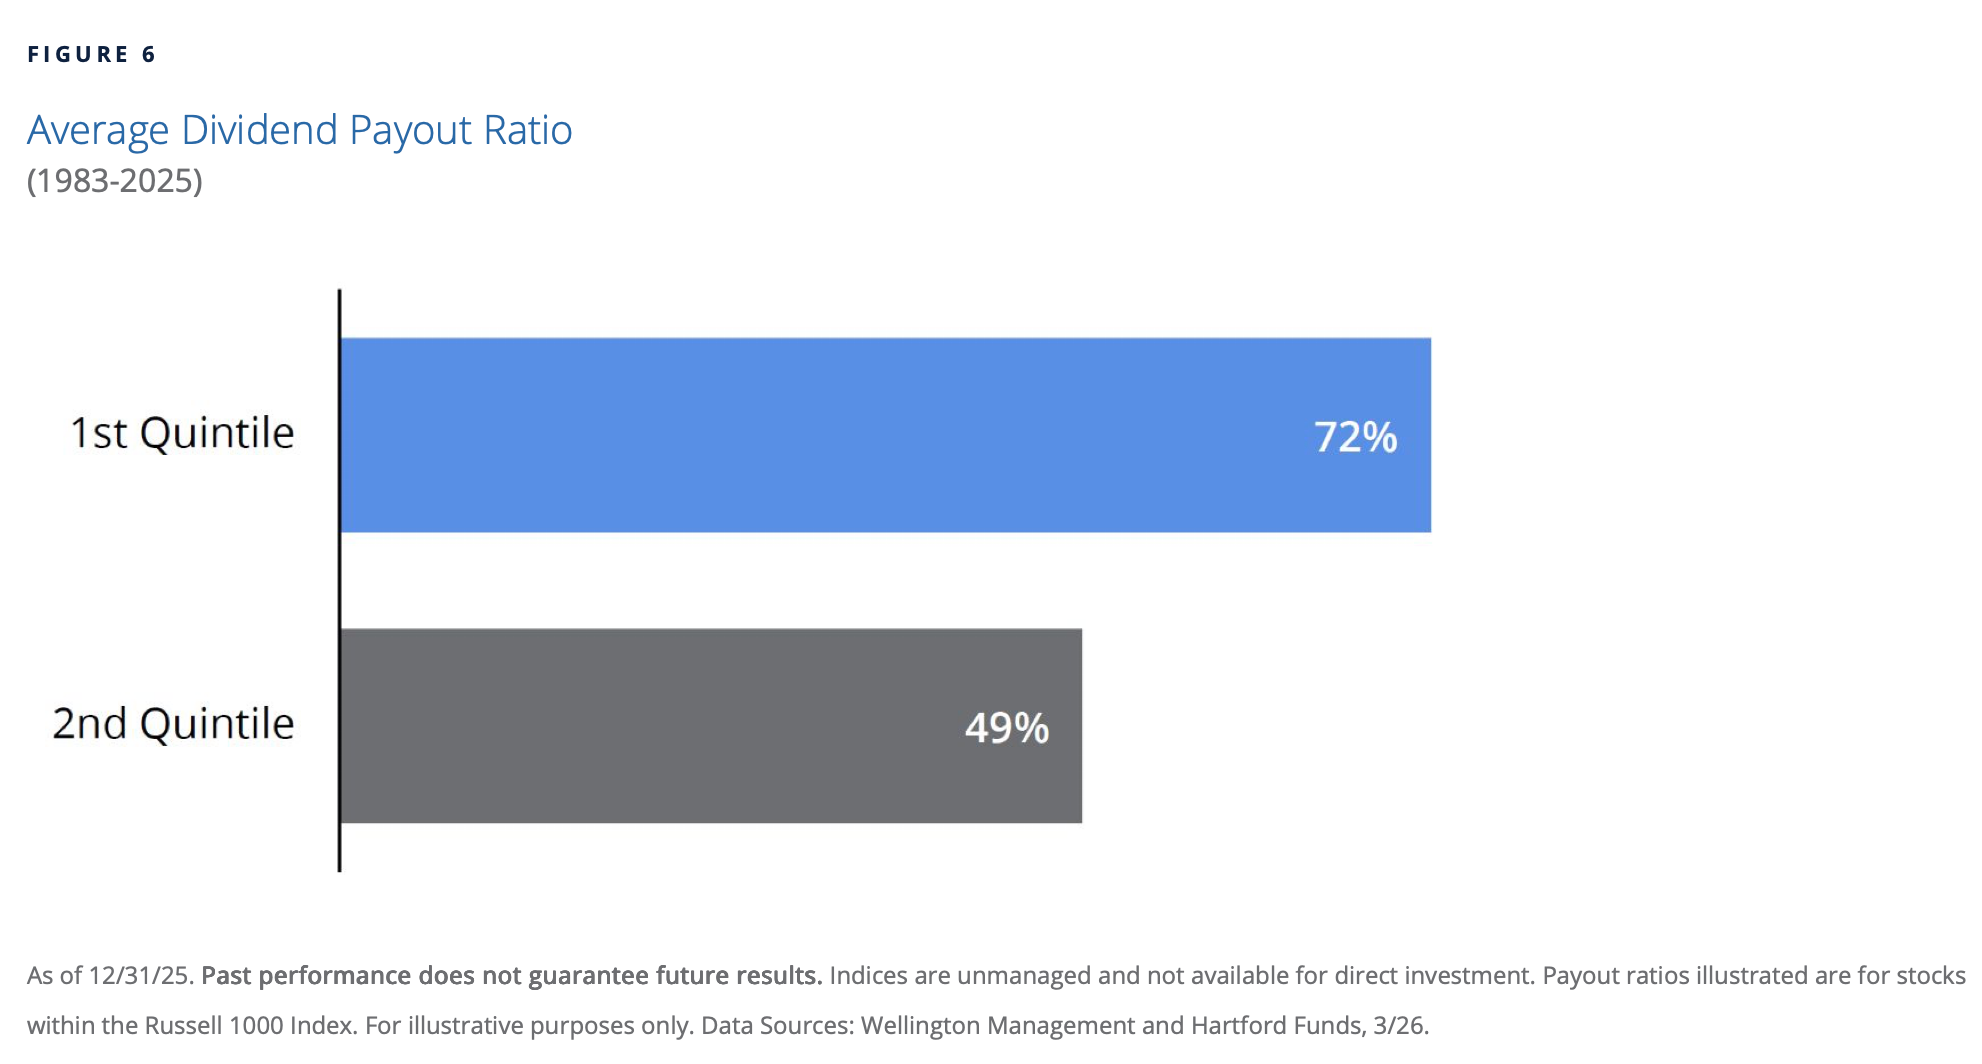
I screened the Russell 1000 to find the companies sitting in that Second Quintile today.
Let’s look at a few that are interesting:
Otis Worldwide (OTIS)
How they make money:
Otis is the world’s leading manufacturer, installer, and servicer of elevators and escalators.
Why They’re Interesting:
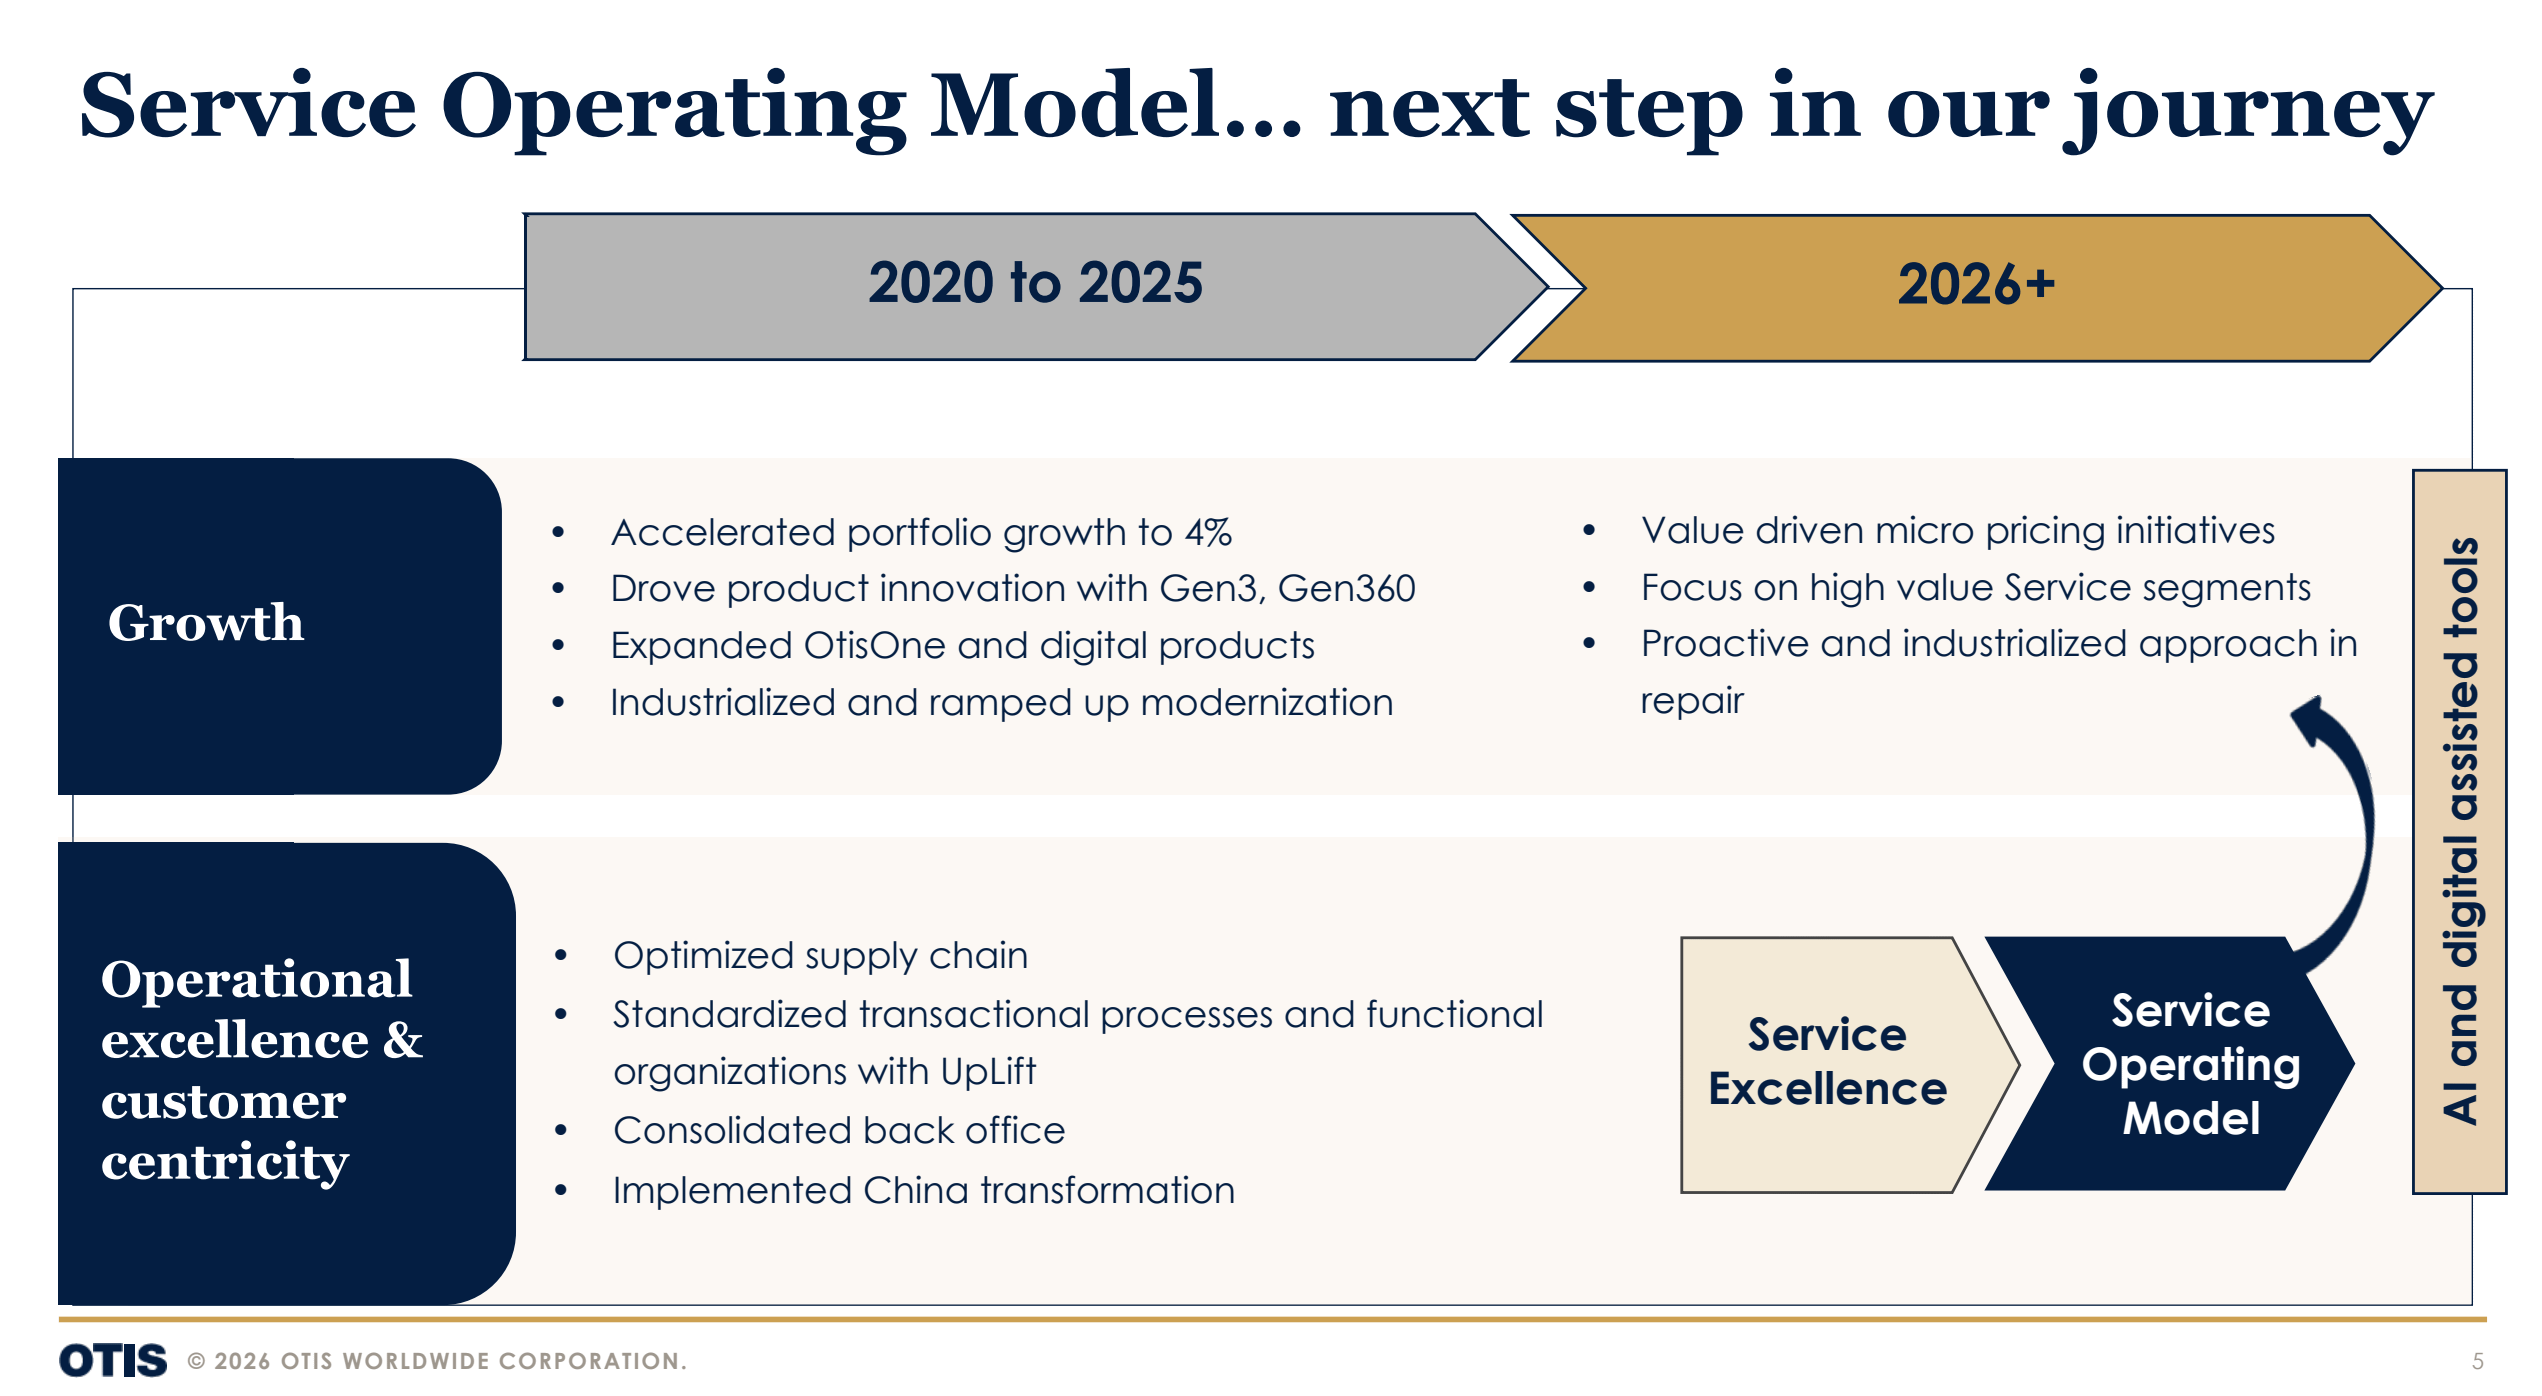
Recurring Revenue: While new equipment sales are cyclical, the real money is made on the back end. Elevators require strict, legally mandated maintenance.
High Consolidation: The global market is an oligopoly dominated by just a handful of major players.
Otis’ Competitive Advantages:
Razor-and-Blade Model: Their massive global installed base feeds high-margin, sticky service and maintenance contracts.
Route Density: They have the largest global number of mechanics, creating efficiencies that regional competitors cannot match.
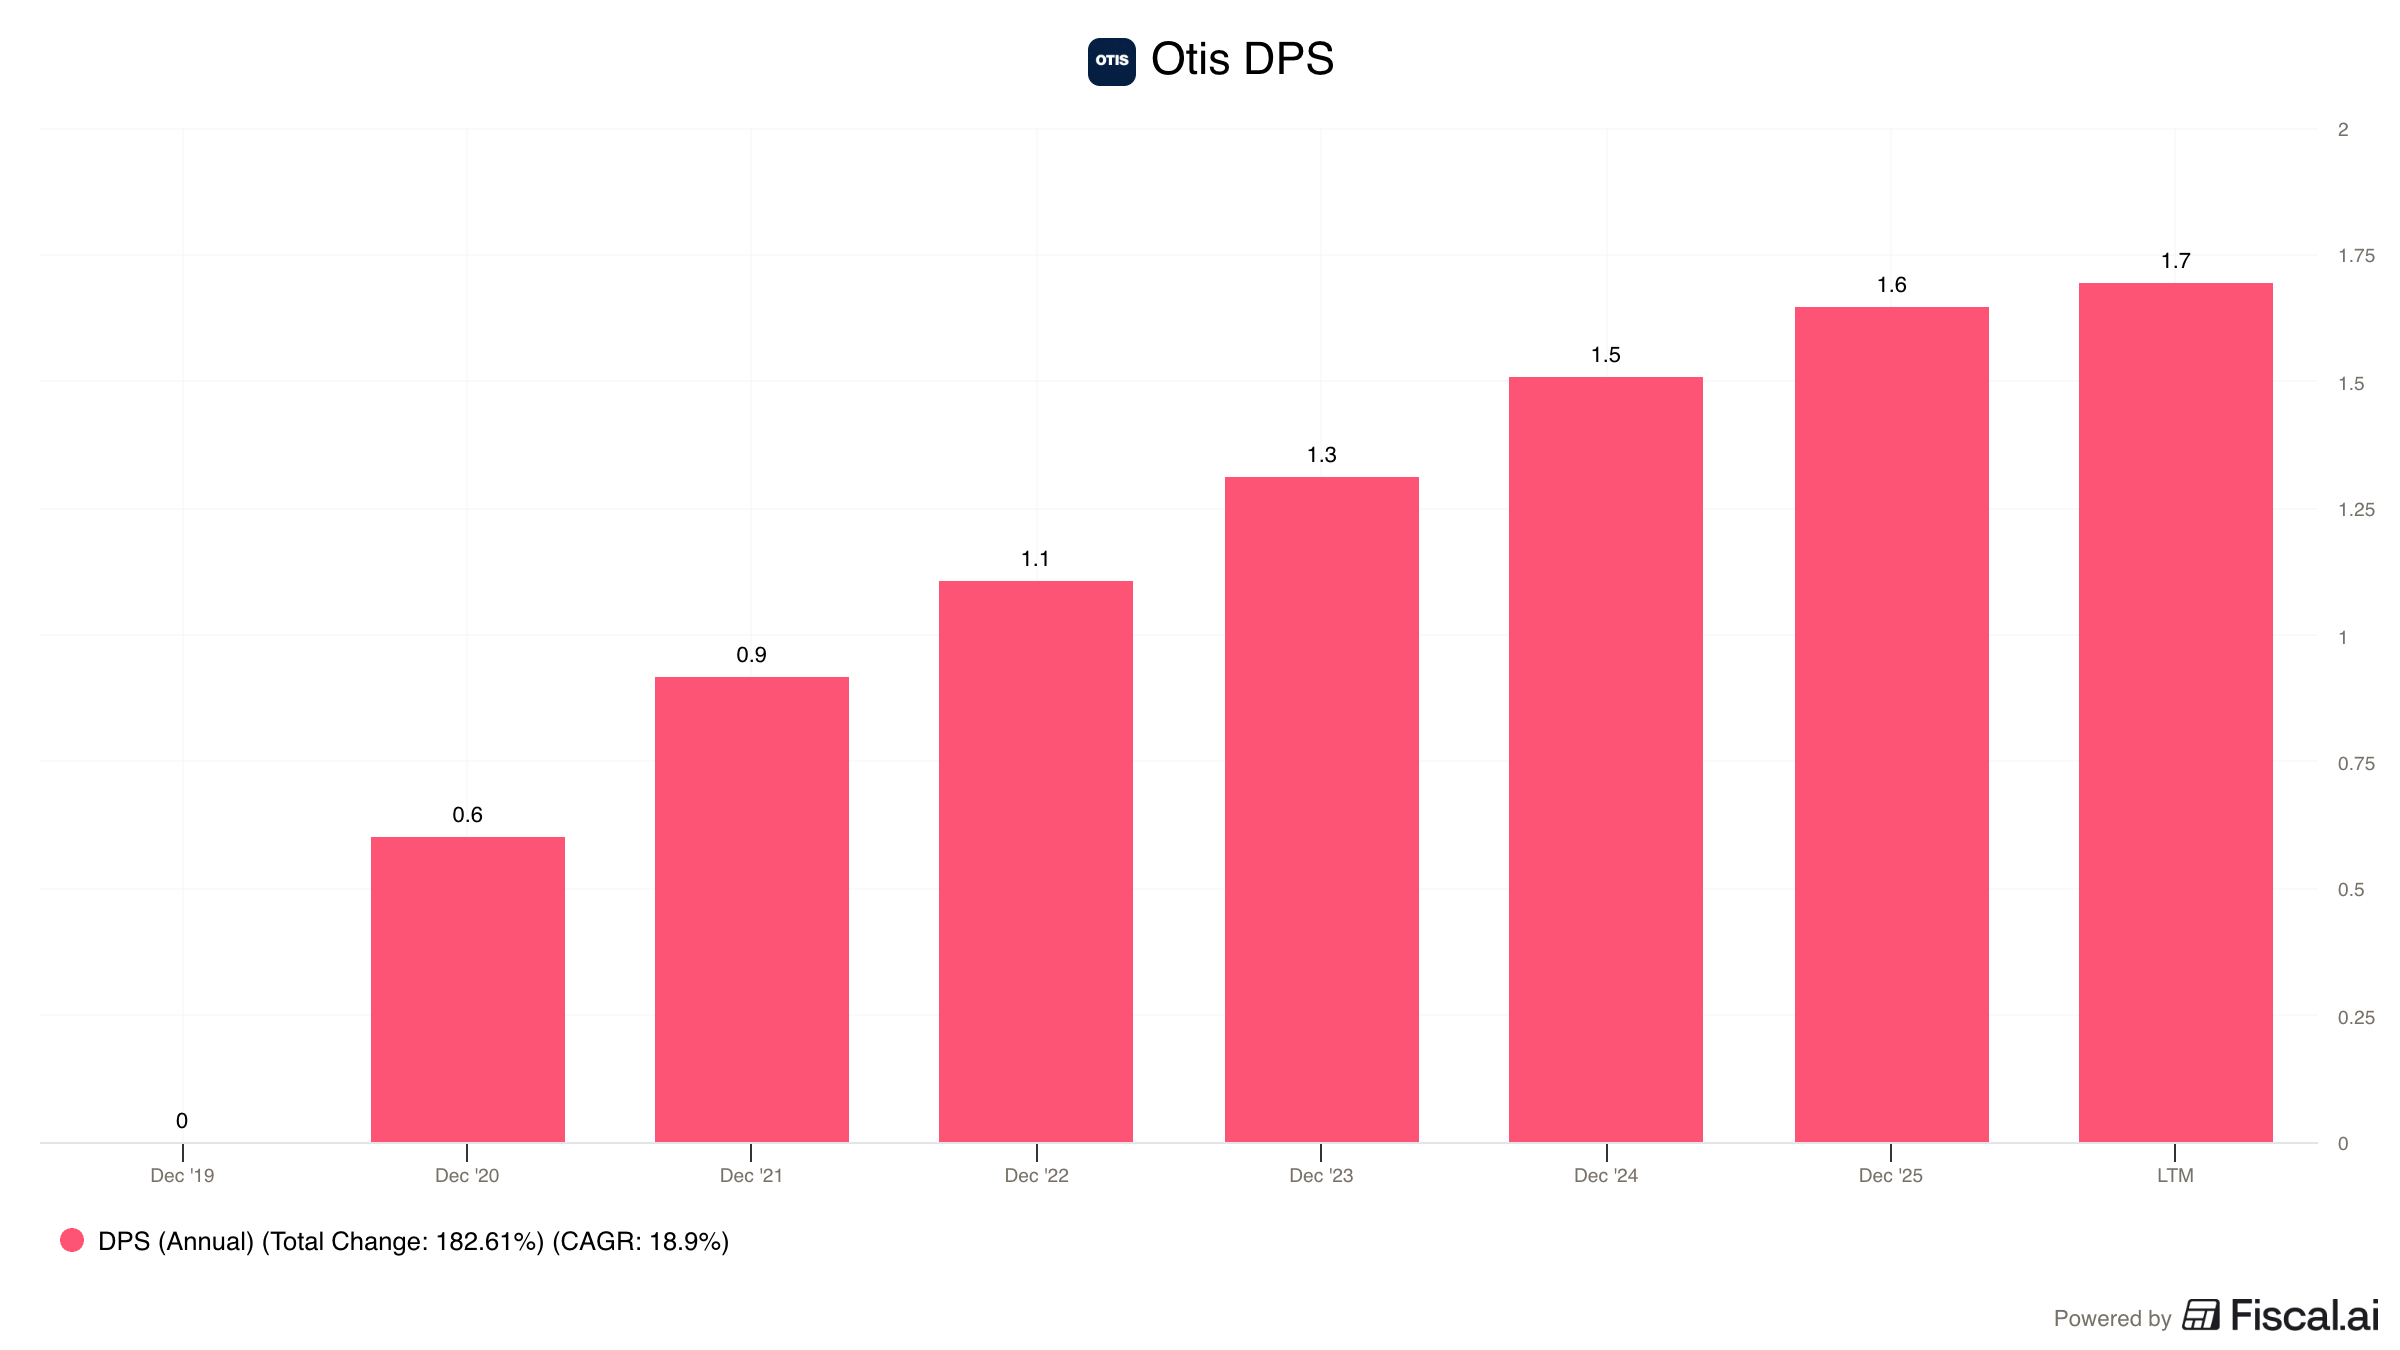
Dividend Yield: 2.51%
5-Year DPS CAGR: 22.32%
Chowder Score: 24.83
Tractor Supply (TSCO)
How they make money:
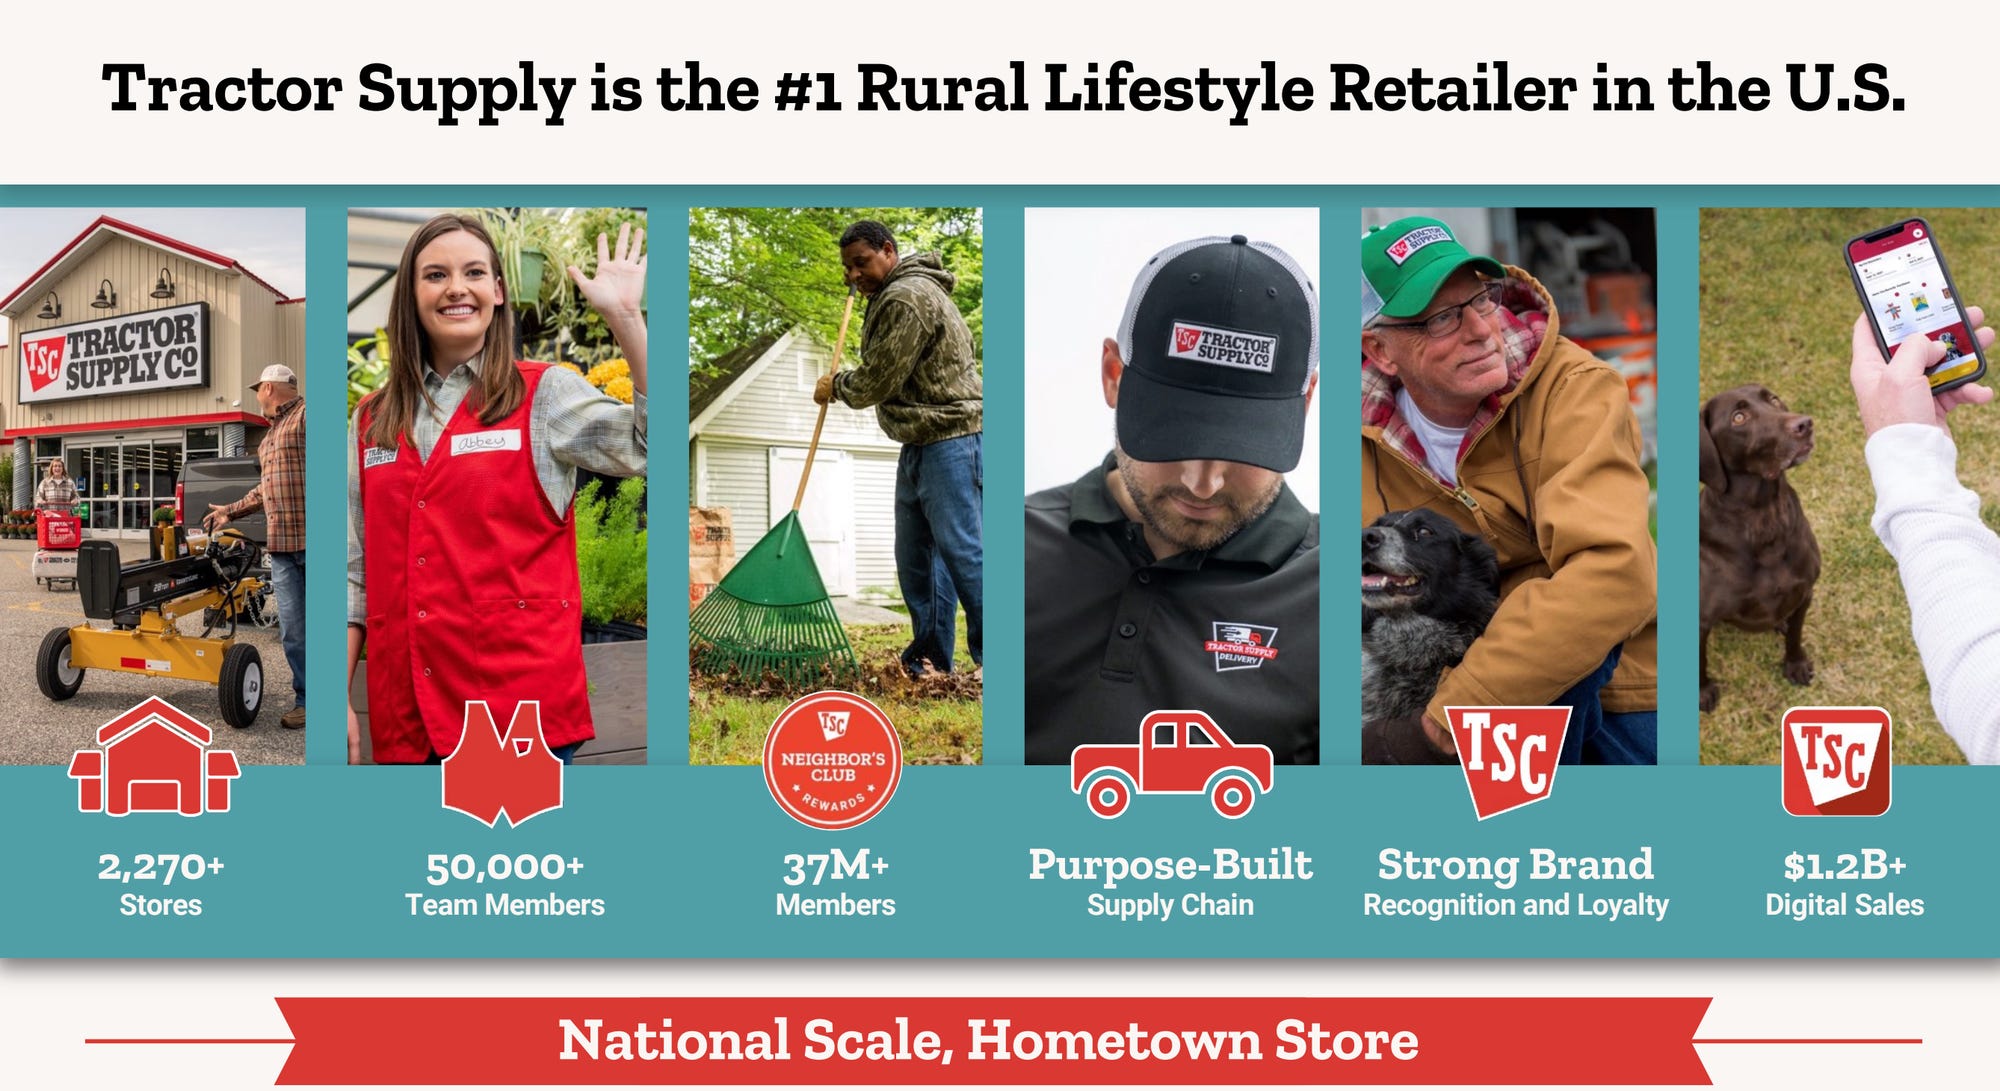
Tractor Supply is the largest rural lifestyle retailer in the United States, supplying everything from livestock feed and agricultural supplies to hardware and workwear.
Why They’re Interesting:
Needs-Based Spending: The bulk of their sales come from consumable, non-discretionary items. Whether there is a recession or not, animals still need to eat.
E-Commerce Resistance: They sell heavy, bulky items (like 50-pound bags of feed or fencing) that are unprofitable for traditional e-commerce companies to ship.
Tractor Supply’s Competitive Advantages
Geographic Moat: Their stores are located outside major urban centers, insulating them from direct Amazon logistics competition.
High Loyalty: Their specialized inventory and knowledgeable staff cater to a specific “Out Here” lifestyle demographic that big-box retailers ignore.
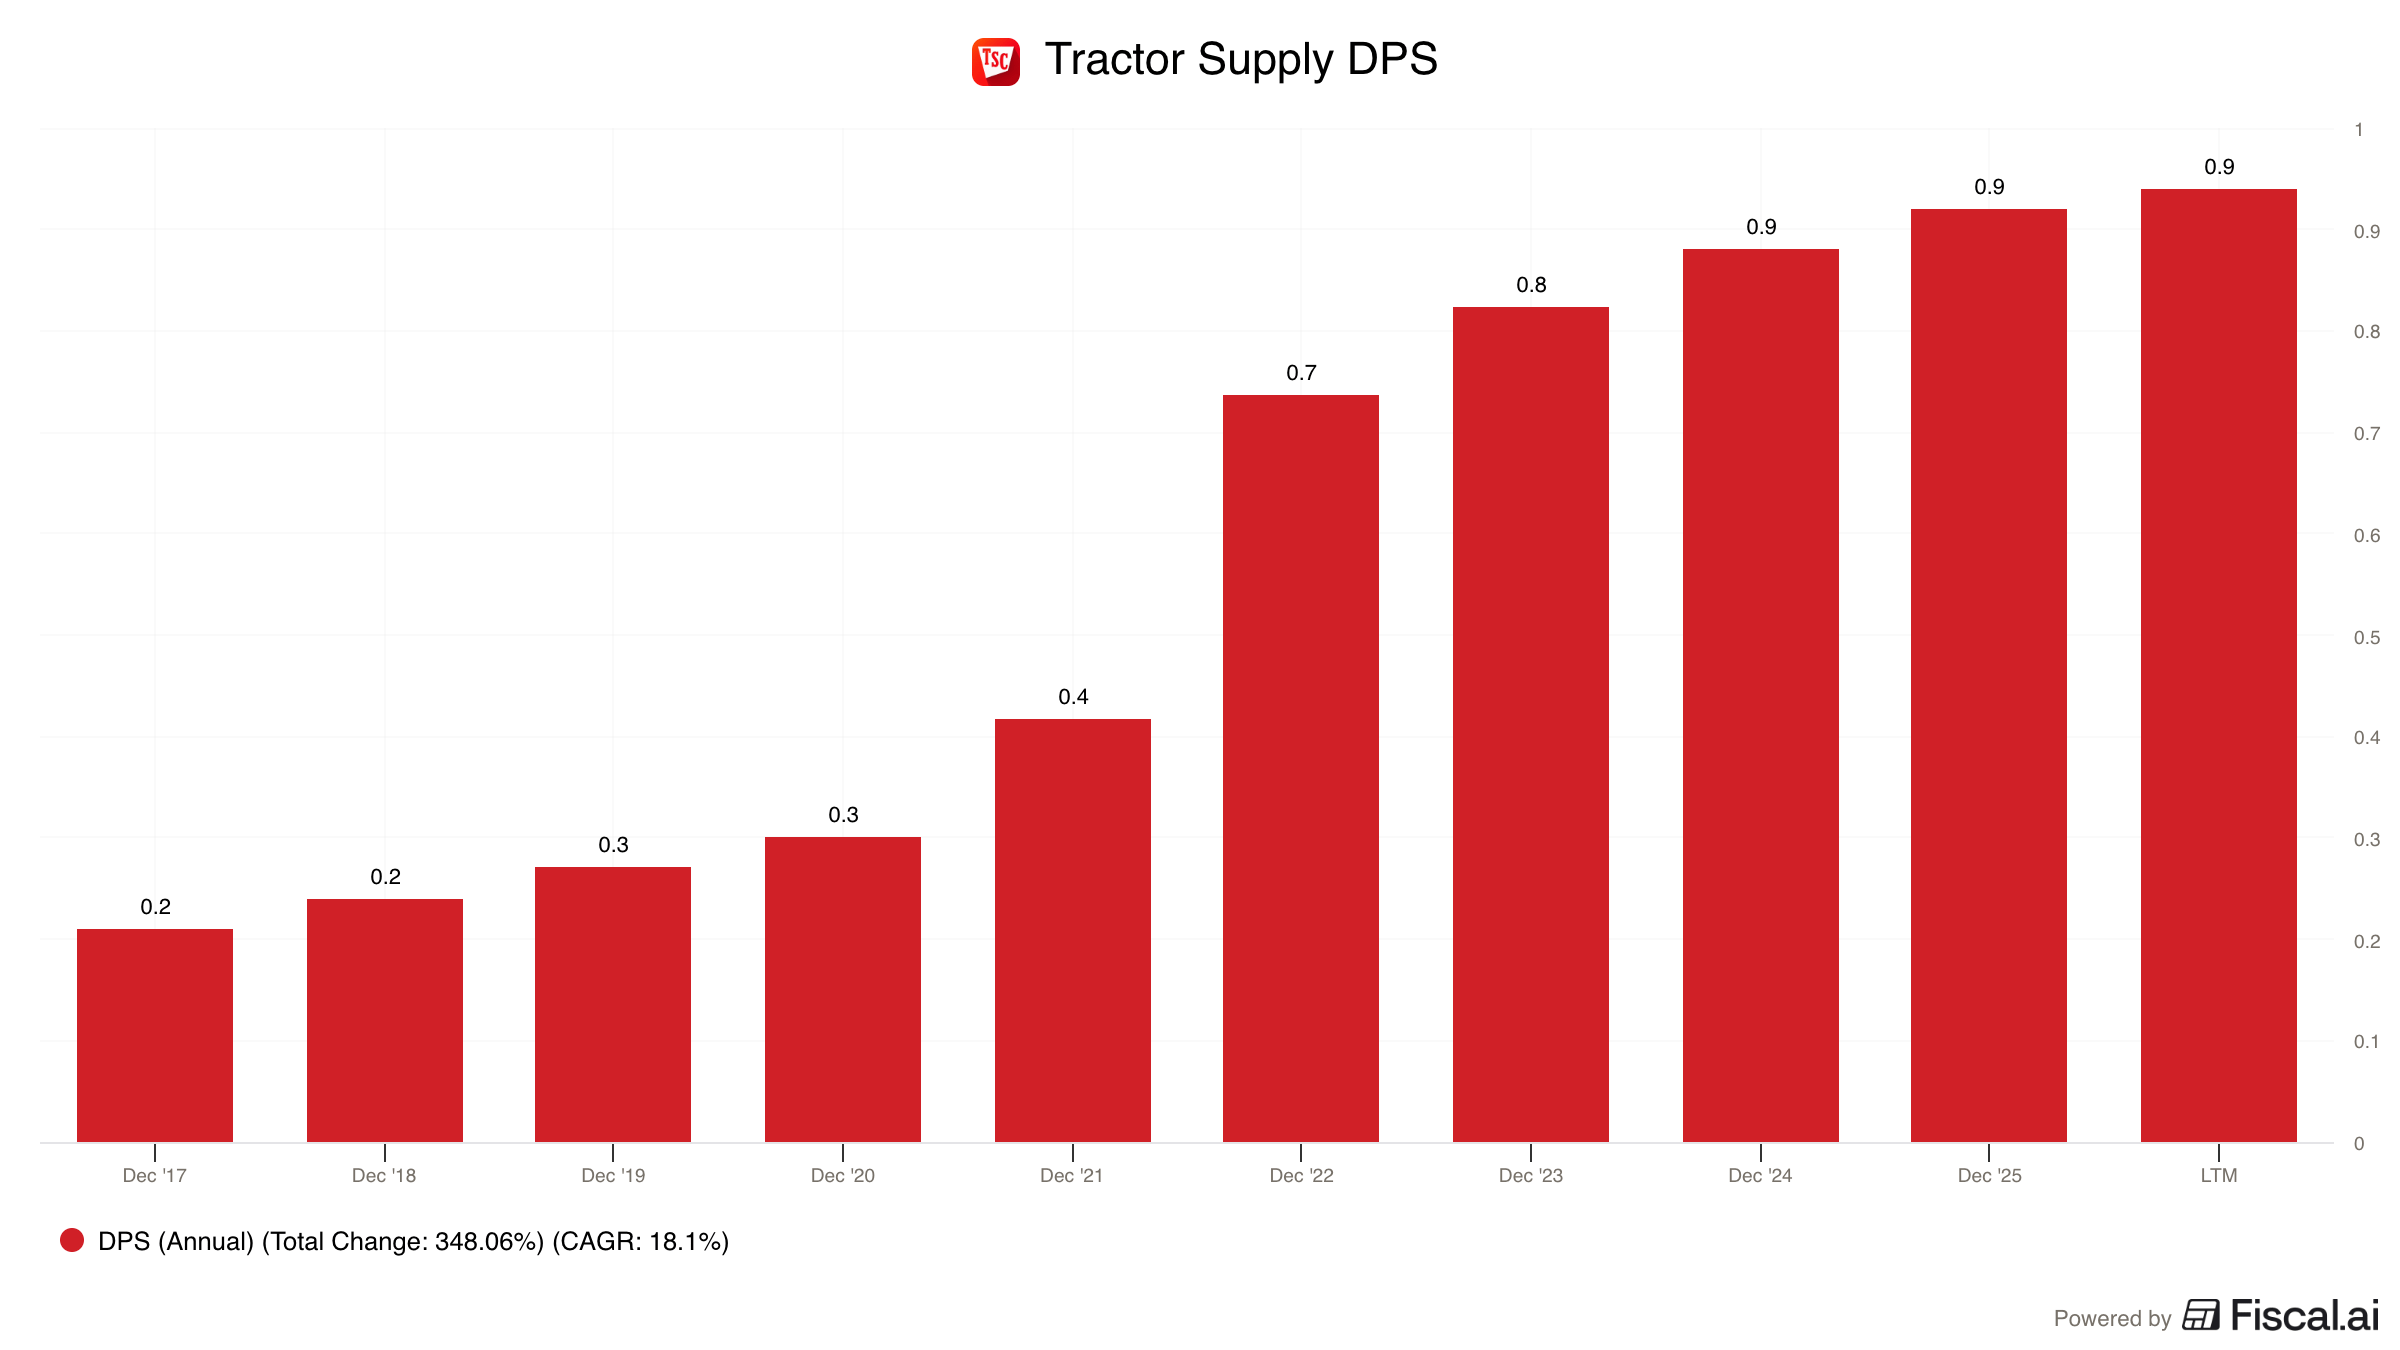
Dividend Yield: 2.95%
5-Year DPS CAGR: 25.11%
Chowder Score: 28.06
Upgrade for more…
Otis and Tractor Supply are phenomenal businesses, but they are only the beginning of this month’s screen.
There are three more 2nd Quintile Compounders on this list with strong market positioning and pricing power.
More importantly, premium subscribers get the screen results, plus the 5-year growth rate and Chowder Score for each company on it.
If you are ready to stop chasing dangerous yields and start building a portfolio of durable, sleep-well-at-night compounding machines, upgrade your subscription today.
Conclusion
The Second Quintile is a great place to search for sustainable and growing dividend yields.
Here are are a few interesting companies that I think fit this criteria:
Otis Worldwide (OTIS): A global elevator oligopoly printing high-margin, recurring revenue from legally mandated maintenance contracts.
Tractor Supply (TSCO): The dominant “rural lifestyle” retailer selling e-commerce-resistant, non-discretionary agricultural supplies and feed.
One Dividend At A Time,
-TJ
Used sources
Interactive Brokers: Portfolio data and executing all transactions
Fiscal.ai: Financial data
Disclaimer
As a reader of Compounding Dividends, you agree with our disclaimer. You can read the full disclaimer here.